Ravi walked into Shyam’s office holding a cup of chai, looking a bit tired. He turned 55 last week.
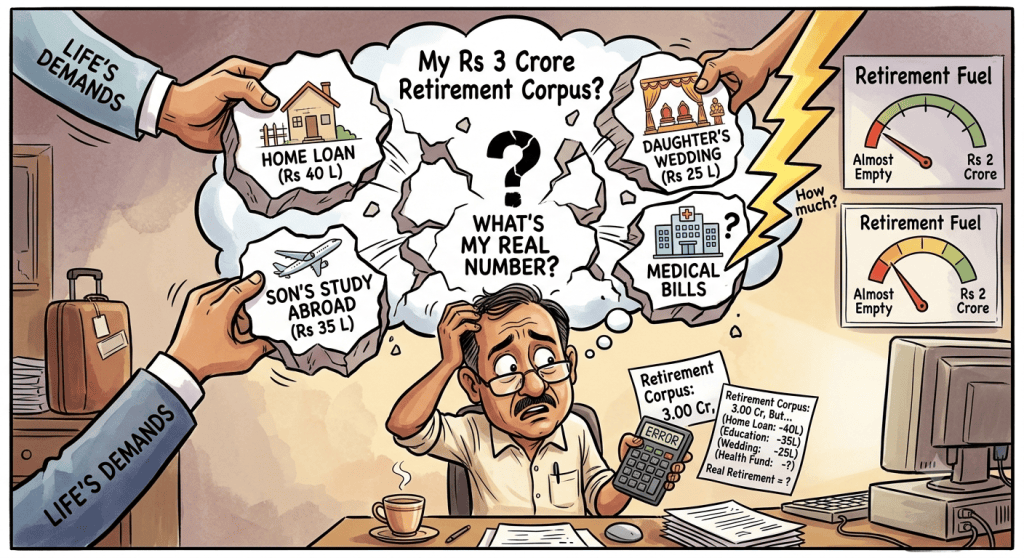
Ravi: Shyam bhai, I have saved Rs 3 crore. I want to stop working at 60. Is that enough?
Shyam: Good that you’re asking now, not at 60. First tell me — what does your house spend every month? Like, if you add up groceries, electricity, maybe a movie or two.
Ravi: Around Rs 90,000. Simple life. No rent, since the house is paid off.
Shyam: Okay, here’s an easy trick. Take that monthly number and multiply it by 350. Think of it like buying enough “fuel” to run your life for many years without stopping at the pump too often.
Ravi: 90,000 times 350… that’s about Rs 3.15 crore. I have Rs 3 crore. So I’m almost there?
Shyam: Almost. But there’s a second rule. Don’t take out more than 6 rupees for every 100 rupees you have, each year. It’s like a water tank — if you keep the tap too open, it runs dry fast. Keep it just right, and it refills a little every year even while you’re using it.
Ravi: Okay, sounds manageable.
Shyam: Now let me ask something that stings a bit. That Rs 3 crore — is all of it really for you?
Ravi: What do you mean, it’s my money.
Shyam: Think of it like your fridge. It’s your fridge, but if half of it is already packed with food for a family function next week, is it really “your” fridge for daily use right now? Let’s check. Any loan still running?
Ravi: Yes. Home loan, another 8 years to go. About Rs 40 lakh left.
Shyam: Your son?
Ravi: Wants to study abroad in three years. We already told him yes. That’s around Rs 35 lakh.
Shyam: Daughter’s wedding?
Ravi: (smiles awkwardly) Yes… we’ve been quietly saving for that too. Maybe Rs 25 lakh.
Shyam: So add it up — Rs 40 lakh, Rs 35 lakh, Rs 25 lakh. That’s Rs 1 crore already “booked,” like seats reserved on a train before you even reach the station. What’s actually free for you?
Ravi: Rs 2 crore.
Shyam: Right. And Rs 2 crore is not 350 times your monthly spend anymore — it’s closer to 220 times. So the number that looked comfortable on paper was already half-promised to other people. It was never fully yours to relax with.
Ravi: That’s a bit of a wake-up call.
Shyam: It usually is. But it’s better to know now than to find out at 70. Just write down everything you’ve promised — loans, weddings, kids’ education — and subtract it honestly. Whatever remains, that’s your real number.
Ravi: Understood. What else should I know?
Shyam: Health. Tell me — is a hospital bill part of your Rs 90,000 monthly budget?
Ravi: No, that’s separate. We have insurance.
Shyam: Good start, but insurance is like an umbrella — it helps, but it doesn’t always keep you fully dry in heavy rain. Say your father needs heart surgery. Bill comes to Rs 15 lakh. Insurance covers Rs 6 lakh. Where does the remaining Rs 9 lakh come from?
Ravi: From my savings, I guess. My retirement money.
Shyam: That’s what most people do, and here’s the surprising part. Even if you’re careful and only withdraw your usual 6%, that one big bill quietly makes your yearly income smaller for many years after — like a bruise that doesn’t hurt every day, but slows you down for a long time. You don’t go broke. You just live a little tighter, every single year, without knowing exactly why.
Ravi: That sounds like something that could sneak up on anyone.
Shyam: Exactly. So I tell people to build three simple layers, like keeping three different pockets. Pocket one — good health insurance with a top-up, so bigger bills are covered better. Pocket two — a separate medical fund, kept apart from your retirement money, just for these moments. Pocket three — a credit card with a high limit or a ready credit line.
Ravi: Why the credit card if I already have a medical fund?
Shyam: Because hospitals don’t ask if the stock market is having a bad week. If you’re forced to sell your investments during a market dip just to pay a bill, you lose more than you should. The credit line buys you three or four weeks — like a short bridge — so you can calmly move money from your medical fund instead of panic-selling.
Ravi: Makes sense. Now, how many years should I actually plan for? I was thinking maybe 25 years after retirement.
Shyam: Here’s a simple way to think about it. If you’re healthy at 60, you’ve already crossed many hurdles that shorten the “average” life expectancy number — accidents, early illness, and so on. So your real number is likely longer than the average. Plan for 30 to 35 years, not 20 or 25. Think of it like packing for a trip — better to carry a little extra than run short halfway.
Ravi: And what about my wife?
Shyam: Plan around whoever is likely to live longer, not an average of both of you. Women usually live a couple of years more than men on average. So if it’s likely she outlives you, her retirement plan should be sized for her — not shortened to match yours.
Ravi: Shyam, I came in feeling confident, and now I have a proper to-do list.
Shyam: That’s a good place to be. None of this needs a finance degree — just honesty with yourself. List what you’ve promised others. Subtract it. Build your three health pockets. And plan for more years than feels comfortable. Do this, and the number you retire will truly be yours to enjoy.
Ravi: (smiling, finishing his chai) Alright. Let’s make that list together.